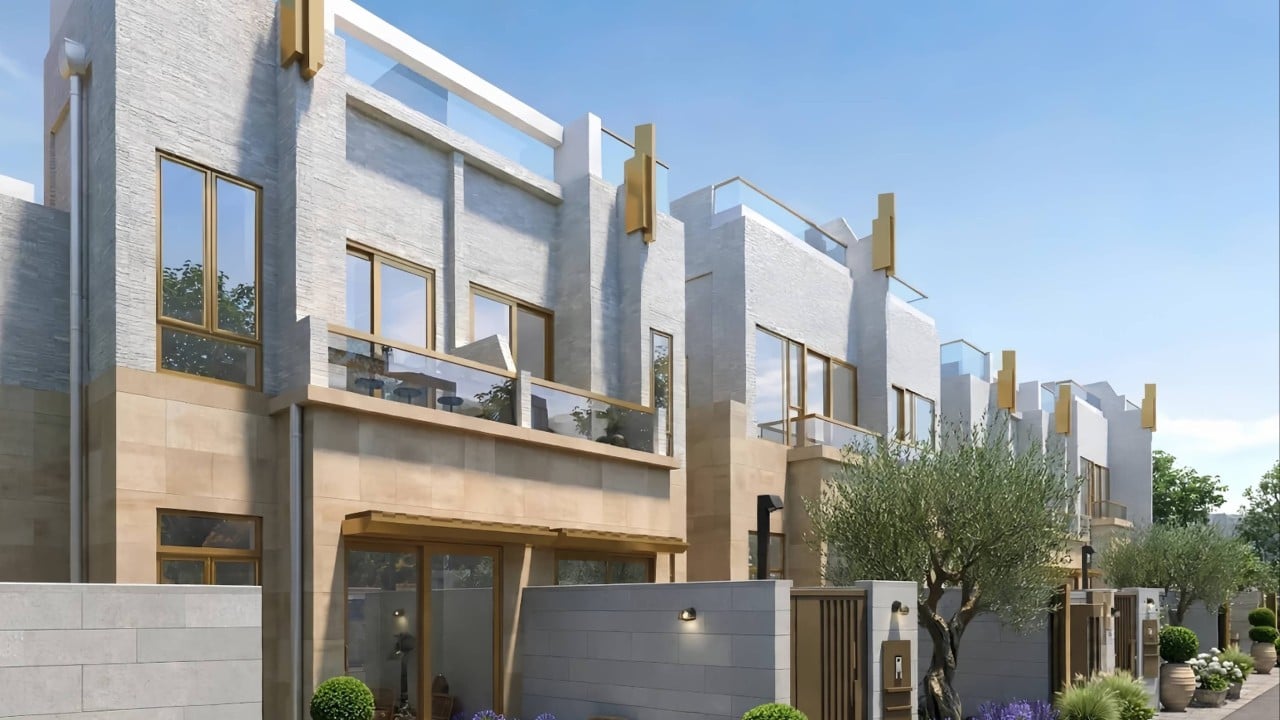
When CK Asset Holdings halts the sales launch of a major residential project like the Montage development in Yuen Long, surface-level market commentary typically reduces the move to reactive pessimism over Hong Kong property sentiment. That reading misses the underlying operational mechanics. A Tier-1 developer suspending an active sales pipeline is rarely an act of panic; it is an exercise in optionality preservation, balance sheet defense, and margin floor protection within a distorted liquidity environment. To understand why CK Asset stepped back from bringing Montage to market, one must deconstruct the structural friction between primary market pricing power, secondary market clearing prices, and the cost of carrying inventory on a low-leverage balance sheet.
The Structural Anatomy of a Primary Launch Freeze
In Hong Kong’s primary residential market, developers operate under strict regulatory timelines governed by the Residential Properties (First-hand Sales) Ordinance, alongside internal return-on-equity hurdles. Launching a project requires committing substantial upfront capital to marketing, show flats, broker commissions, and price-list lock-ins. Once a first price list is published, a developer’s pricing flexibility narrows dramatically; cutting prices on subsequent batches alienates early buyers, triggers reputational friction, and establishes a lower valuation benchmark for bank appraisers across the entire district.
Pausing the Montage launch in Yuen Long interrupts this commitment cycle before irreversible price discovery occurs. Yuen Long sits within the New Territories Northwest corridor—a sub-market characterized by high future supply elasticity due to ongoing Northern Metropolis land releases and heavy reliance on end-user, mortgage-sensitive buyers rather than cash-rich luxury investors. When transaction velocity slows in this segment, launching into weak absorption forces a binary choice: accept anemic take-up rates that signal distress to the broader market, or slash launch prices to clear inventory at the expense of gross margin.
CK Asset’s decision reflects a third path: withholding supply to preserve the option value of the underlying land bank. In real options theory, an unlaunched residential project is equivalent to an American call option on future housing prices, where the strike price is the remaining construction and marketing cost. When market volatility spikes and near-term expected returns turn negative, exercising the option immediately destroys value. Holding the asset unlaunched preserves upside exposure if financing conditions ease, while capping downside brand damage.
Three Variables Governing Developer Holding Power
Not every Hong Kong developer can afford to freeze a launch. The capacity to pause sales at a scale project like Montage depends on three distinct financial and operational variables:
Net Gearing and Debt Service Coverage
Developers carrying high net debt-to-equity ratios face rigid covenant schedules and refinancing walls. For leveraged peers, inventory must be converted into cash flow regardless of margin compression because interest expense compounds daily. CK Asset historically maintains one of the lowest net gearing ratios among major Hong Kong conglomerates. Without immediate debt-service pressure forcing cash generation at any price, the company’s cost of waiting is limited to the opportunity cost of tied-up equity rather than existential liquidity stress.Land Cost Basis and Margin Cushion
The viability of pausing versus discounting depends on the historical acquisition cost of the site. Projects acquired at peak land auction prices between 2017 and 2021 operate with razor-thin buffers; delaying sales risks further erosion if macro headwinds persist. Conversely, sites secured through agricultural land conversion, private treaty grants, or disciplined counter-cyclical bidding carry a lower embedded cost basis. Even where margins are healthy, releasing units into a market where buyers demand steep discounts transfers wealth from the developer’s shareholders to opportunistic purchasers.Sub-Market Supply Saturation
Yuen Long and neighboring Tin Shui Wai frequently experience localized supply gluts when multiple developers attempt to capture the same pool of first-time homebuyers simultaneously. Broker commission wars—where developers offer rebates up to double-digit percentages of the transaction value to incentivize agents—erode net realized prices even when headline price lists appear stable. Pausing Montage allows competitors to exhaust their immediate inventory and absorb the high customer-acquisition costs of a sluggish market, clearing the runway for a cleaner launch window later.
The Pricing Trap in Hong Kong Primary Real Estate
A critical dynamic overlooked by casual observers is the feedback loop between primary launch pricing and secondary market valuations. Hong Kong banks rely heavily on comparable transaction data and developer price lists to determine mortgage loan-to-value appraisals.
If CK Asset launches Montage at a deep discount to stimulate volume—a tactic the company has selectively deployed at other urban projects like Coast Line II in Yau Tong when aiming to shock the market into clearing—the ripple effect in Yuen Long is immediate. A discounted benchmark in Yuen Long depresses valuations across neighboring estates, tightening credit availability for secondary buyers who depend on higher appraisals to fund down payments. That credit contraction further dries up market liquidity, creating a self-reinforcing downward spiral.
By choosing to pause rather than discount at Montage, CK Asset signals that the clearing price required to move units in Yuen Long currently sits below its internal hurdle rate. The market is effectively in a bid-ask standoff: buyers are anchoring expectations to distressed secondary transactions and elevated mortgage rates, while the developer refuses to validate those trough valuations with fresh primary supply.
Operational Mechanics of a Launch Suspension
When a developer halts a sales rollout, specific internal adjustments occur across capital allocation and project management:
- Marketing and Sales Burn-Rate Reduction: Show flat operations, digital ad spend, and external agency retainers are scaled back immediately to stop cash leakage while sales momentum is stalled.
- Construction Phasing Adjustments: While structural work typically proceeds to meet Occupation Permit deadlines, interior fit-out schedules and bulk material procurement can be paced to align with revised handover timelines.
- Product Mix Re-engineering: A pause provides time to reassess unit layouts, financing schemes, and payment plans. In a high-rate environment, developers often shift from straight price cuts to bespoke financing—such as developer-backed second mortgages or extended completion payment schedules—that preserve headline asset values while lowering the buyer’s immediate cash hurdle.
Distinguishing Tactical Pauses from Structural Retreats
Analysts tracking Hong Kong property equities must separate tactical timing adjustments from structural impairment. A tactical pause occurs when fundamental demand for the asset class remains intact over a medium-term horizon, but short-term friction—such as interest rate uncertainty, seasonal slowdowns, or competing launches—temporarily distorts price discovery. A structural retreat occurs when demographic shifts, permanent supply overhangs, or regulatory changes permanently impair the terminal value of the development.
Yuen Long presents a hybrid profile. Over the long term, infrastructure integration with Shenzhen and the broader Northern Metropolis framework underpins housing demand in the northwest New Territories. In the short term, however, elevated HIBOR levels keep mortgage servicing costs high relative to rental yields, eliminating the positive carry that historically drove investor participation. Owner-occupiers, left as the primary demand engine, remain highly sensitive to monthly repayment ratios and macro employment stability.
Limitations of the Waiting Strategy
Withholding inventory is not a risk-free maneuver. Holding completed or near-completed residential stock exposes a developer to three primary vulnerabilities:
- Regulatory and Tax Exposure: While Hong Kong shelved its proposed vacancy tax on unsold first-hand residential units in 2020, persistent hoarding of completed inventory by major developers always carries the latent political risk of renewed policy intervention if housing affordability remains a public priority.
- Physical Depreciation and Carrying Costs: Unsold units still require ongoing security, maintenance, insurance, and property management contributions. Over an extended freeze, buildings age without generating yield, gradually eroding the appeal of "brand-new" status relative to newer competing launches.
- Macro Deterioration Risk: Optionality only creates value if future market conditions improve or stabilize. If interest rates remain higher for longer or regional economic growth decelerates further, a developer that passed on clearing inventory at a modest discount today may be forced to clear at a steeper discount twelve months later, having absorbed a year of carrying costs in the interim.
Tactical Framework for Evaluating Developer Moves
Institutional investors and real estate operators evaluating CK Asset’s decision at Montage—and similar pauses across the sector—should track four concrete indicators rather than relying on broker sentiment:
- HIBOR-to-Rental Yield Spread: Monitor the gap between effective mortgage rates (tied to 1-month HIBOR) and gross residential rental yields in the New Territories. Primary launch velocity rarely accelerates sustainably until rental yields approach or exceed borrowing costs, which reactivates investment demand alongside end-users.
- Competitor Absorption Rates in Neighboring Districts: Watch first-day sell-through percentages on peer launches in Yuen Long, Tuen Mun, and Tin Shui Wai. Sell-through rates below 40 percent confirm that the market cannot absorb volume without aggressive price concessions.
- Effective Rebate Structures: Look past headline price lists to the net effective price after cash rebates, stamp duty subsidies, and furniture allowances. When developers quietly expand rebate packages without cutting list prices, it indicates underlying margin stress.
- Land Bank Replenishment Pace: Track whether CK Asset deploys capital into new government land tenders or distressed corporate acquisitions while pausing sales. A developer simultaneously pausing launches and acquiring cheap land is executing a classic counter-cyclical arbitrage—refusing to sell low while buying lower.
The Strategic Play
CK Asset’s decision to pause the Yuen Long Montage launch should be read as disciplined capital preservation rather than corporate distress. In an illiquid, rate-constrained sub-market, forcing supply onto buyers who lack financing leverage destroys margin without building sustainable momentum. The optimal move for a low-geared developer is to lock down marketing burn, hold headline valuations intact, and let more leveraged competitors bear the cost of price discovery in the New Territories. Until effective mortgage rates compress enough to restore positive carry for buyers, expect Tier-1 balance sheets to prioritize margin defense over volume—keeping prime inventory off the table until the bid-ask spread narrows on their terms.