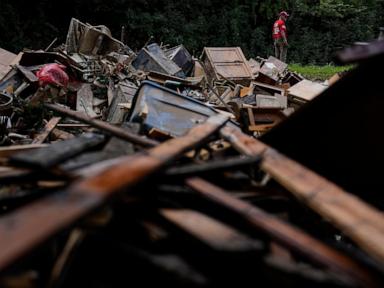
Roughly 86% of high-risk U.S. properties lack National Flood Insurance Program (NFIP) coverage even as average premiums have surged by around 90% over a five-year span. That collision—rising actuarial prices paired with shrinking policy penetration—exposes a structural failure in how America prices, maps, and mandates catastrophe risk.
A standard news report treats this crisis as a frustrating paradox: people who need protection most are dropping or skipping coverage right when extreme rainfall and coastal surges intensify. From a strategy and risk-management standpoint, the paradox is not a mystery. It is the predictable output of an institutional design that conflated cross-subsidization with social safety net policy, anchored mandatory purchase rules to static binary maps, and left disaster recovery aid structured to punish repeat exposure without insurance.
To understand why coverage is contracting while exposure expands, we can map the problem across four structural components: The Mandate Blind Spot, The Pricing-to-Retention Tradeoff, The Disaster Aid Trap, and The Execution Sequence for Risk Reduction.
Deconstructing the Competitor's Argument
The reference coverage captures the human stakes and surface metrics well: roughly 4.5 million NFIP policies in force covering only a small fraction of U.S. properties, typical annual premiums near $1,100 after roughly 90% five-year growth, policy counts down by about half a million over five years, and low-income households hit by severe flooding facing caps on federal disaster grants and bars on repeat uninsured aid.
Where conventional reporting stops short is causal synthesis. It often presents rising prices, outdated maps, and low take-up as parallel complaints rather than linked subsystems in a feedback loop.
- Observation versus mechanism: Noting that premiums rose while policy counts fell describes correlation; tracking price elasticity of demand and lender-mandate enforcement gaps explains why households exit.
- Mapping versus pricing: Treating flood maps and actuarial pricing as a single flaw blurs two distinct functions. Flood maps govern legal compulsion (who a mortgage lender must require to buy coverage), whereas Risk Rating 2.0 governs actuarial price discovery (how risk is calculated per structure).
- Known facts versus hypotheses: Verified institutional facts include the NFIP's statutory mandate since 1968, its multi-billion-dollar debt to the U.S. Treasury (around $22.5 billion), standard residential coverage caps ($250,000 for building and $100,000 for contents), and GAO findings that roughly 86% of high-risk properties lack NFIP policies. By contrast, claiming that any specific household dropped coverage solely due to rate hikes without accounting for mortgage payoffs, local housing turnover, or private market shifts remains an educated hypothesis unless verified at the policy cohort level.
The Mandate Blind Spot
The NFIP was built around a bargain: communities adopt floodplain management ordinances, and in exchange, residents gain access to federally backed flood insurance. Yet mandatory purchase rules apply only to federally backed mortgages on properties located inside mapped Special Flood Hazard Areas (SFHAs)—traditionally modeled around the 1% annual chance (100-year) flood.
This binary boundary creates three systemic blind spots:
- Unmapped pluvial and inland risk: Heavy rainfall and flash flooding frequently overwhelm drainage systems far from major rivers or coastlines. Analyses cited by the GAO and catastrophe modelers indicate millions of high-risk properties sit outside FEMA's mapped flood zones, meaning lenders do not trigger mandatory flood coverage at origination or renewal.
- Unmortgaged ownership: Homeowners who own properties free and clear—including older residents on fixed incomes or long-term rural owners—face no lender compulsion to maintain a policy. When premiums climb, discretionary policies are the first line item cut.
- Lender compliance friction: Even inside mapped zones, mortgage servicing compliance and escrow enforcement vary, leaving a substantial share of high-risk structures uninsured.
The first consequence of this blind spot is adverse selection in reverse: low-awareness or low-income households outside mapped zones remain exposed to severe losses without early risk signals, while households inside mapped zones face sharp pricing adjustments.
The Pricing-to-Retention Tradeoff
For decades, the NFIP suppressed premiums on many older or high-exposure buildings through cross-subsidies and grandfathered rates. While that kept initial bills lower, it starved the program of actuarial revenue and contributed to tens of billions of dollars in Treasury debt.
Risk Rating 2.0 shifted the pricing engine toward property-specific risk factors—including flood frequency across multiple sources, distance to water, first-floor height, replacement cost, and prior loss history—subject to statutory annual increase glidepaths.
Why Actuarial Accuracy Collides with Affordability
Actuarial pricing solves a solvency problem, not an affordability problem. When a policy moves from a subsidized rate toward full-risk pricing, two forces collide:
- Income inelasticity at the low end: For households earning modest incomes, a jump of several hundred to several thousand dollars per year represents a severe budget shock. Even when the long-run expected value of insurance is favorable relative to catastrophic damage, liquidity constraints force policyholders to lapse.
- Subjective probability discounting: Homeowners routinely weigh rare, high-severity events against certain annual cash outflows. A property owner who has not flooded in decades—or who views a past flood as a once-in-a-lifetime anomaly—often underweights tail risk when renewal bills spike.
The Limitation of Market-Only Fixes
A common consultant reflex is to argue for handing the entire market to private insurers. Private flood carriers can offer higher coverage limits, faster underwriting, and specialized terms such as business interruption coverage that standard NFIP policies lack. However, private insurers price strictly to risk and return targets; they do not solve affordability for low-income households in chronic floodplains, nor do they resolve public-sector disaster fiscal exposure on their own.
The Disaster Aid Trap
Many uninsured homeowners assume federal disaster aid will make them whole after a flood. That assumption misreads how disaster relief operates.
FEMA individual assistance is designed for emergency stabilization and basic habitability—not full replacement or wealth restoration—and average payouts per homeowner are a fraction of typical insured flood claims. Worse, statutory rules restrict repeat disaster aid for uninsured properties in designated flood zones after an initial payout.
When an uninsured household suffers a second flood in a mapped zone without carrying coverage required after prior assistance, federal aid rules can cut off future recovery grants—leaving the owner with structural damage, diminished equity, and limited borrowing capacity.
Consider a household with a modest annual income whose home is damaged by inland or valley flooding. Emergency grants cover immediate essentials and partial repairs, while uninsured structural losses force debt or deferred maintenance. If a subsequent storm hits without active coverage, the household faces a compounding balance-sheet shock. Buyout programs offer a permanent exit in select cases, yet funding queues, local match requirements, and voluntary participation limits mean buyouts scale slowly relative to regional exposure.
Operational Playbook for Closing the Protection Gap
Fixing flood risk requires separating risk pricing, targeted affordability, and physical mitigation rather than forcing one policy instrument to carry all three burdens.
- Audit true property-level hazard beyond zone labels. Do not rely solely on whether a parcel sits inside or outside a legacy flood zone. Evaluate elevation, drainage paths, local rainfall intensity, and prior claim history to separate true low-risk properties from under-mapped high-risk assets.
- Benchmark NFIP against private flood quotes. Compare NFIP's standardized limits ($250,000 building and $100,000 contents caps for residential policies) and waiting periods against private market options, especially for higher-value homes or commercial properties needing business interruption protection.
- Pair insurance decisions with physical mitigation. Lowering flood exposure through elevation, flood vents, utility relocation, or drainage improvements reduces expected annual loss at the source instead of merely financing recurring damage.
- Decouple income support from distorted rate signals. Where affordability is the binding constraint, policy design works best when means-tested assistance is funded explicitly rather than by suppressing risk signals for wealthy or low-risk properties.
Every recommendation carries constraints. Updated flood modeling takes years to roll out and faces political pushback when mapped risk expands. Means-tested subsidies require explicit fiscal appropriations and income verification. Structural elevation is capital-intensive and often impractical in low-income communities without substantial grants.
Strategic Forecast and Recommendation
Over the next cycle, uninsured flood losses will continue to rise faster than insured flood losses whenever severe storms hit under-penetrated inland and low-to-moderate-income markets. Relying on ad-hoc post-disaster appropriations after major floods will remain fiscally reactive and inequitable because aid arrives after wealth is already destroyed and reaches only a subset of affected owners.
The decisive strategic move for policymakers, lenders, and institutional risk managers is to re-architect protection around three parallel tracks: modernize hazard disclosure so buyers see granular flood risk before closing; direct targeted, transparent affordability support to low-income households in high-exposure areas rather than broad rate distortions; and tie hazard mitigation financing directly to repeat-loss properties and buyout corridors before the next storm cycle strikes.