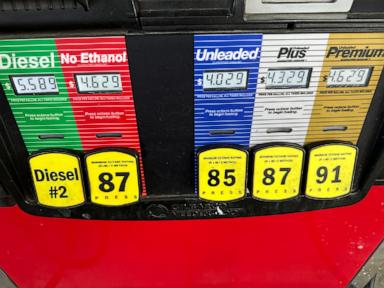
Prices are technically rising slower than they used to, but your grocery bill still hurts. Everyone keeps talking about cooling inflation metrics like it is a miracle cure for household budgets, yet everyday expenses remain stubbornly high. You go to the supermarket, drop a hundred bucks, and leave with half the bags you used to get five years ago.
Economic reports love to celebrate the macro numbers. They point to index trends showing that price spikes have moderated compared to the frantic surges of the post-pandemic era. But macroeconomics and your checking account speak two entirely different languages. While the rate of price increases slows
Why Inflation Cooling While We Spending Makes Total Sense
business
You look at your bank account after a weekend out and wonder how prices can possibly be slowing down while your card keeps getting lighter. Economics reports talk about inflation easing up. At the exact same time, retail data shows shoppers hitting stores and buying more stuff. It feels like a massive contradiction.
It isn't.
Most people misunderstand how price cooling interacts with consumer behavior. We assume that if inflation drops, people magically stop spending, or that heavy spending automatically forces prices back through the roof. That framework misses the underlying mechanics of modern consumer resilience, changing supply chains, and shifting household priorities. Let's break down why inflation cooling while spending stays hot is actually the current economic reality.
The Cost of Living Reality Check
Prices aren't actually dropping. When economists say inflation is cooling, they don't mean groceries cost less than they did last year. They mean prices are rising slower than they were previously.
Think about it like driving a car. If you are going ninety miles an hour and ease off the gas until you are cruising at sixty, you are still moving forward fast. You aren't reversing. You just aren't accelerating as aggressively as before.
This distinction causes massive confusion. Households hear inflation is cooling and expect immediate relief at the register. When that relief looks more like a slightly smaller price hike than an actual discount, frustration sets in. Yet people keep buying because life demands it. You still need gas, rent, utilities, and coffee.
People adjust their baselines. Once you absorb a massive price shock over a couple of years, your brain normalizes the new baseline. You stop comparing today's prices to 2019 and start managing your weekly cash flow around 2026 realities. Spending adapts because it has to.
Why Consumers Refuse to Stop Buying
Consumer spending refuses to break because the labor market and wage growth kept a floor under household budgets. Even with higher borrowing costs, employment numbers stayed steady enough to keep paychecks coming in.
We also see a psychological shift in how younger generations view money. Saving for a distant milestone feels less appealing when housing markets remain heavily locked down and economic uncertainty feels like the permanent default setting. The logic shifts from saving every penny for a vague future to enjoying experiences right now. Travel, dining out, and entertainment capture a larger share of the wallet than traditional savings accounts.
Supply chains also healed. During the post-pandemic bottlenecks, scarcity drove prices into orbit because businesses could charge whatever they wanted and people would pay to secure scarce goods. Now that inventory flows smoothly again, intense competition forces companies to moderate price increases. Supply caught up with demand. That cooling trend shows up in the official numbers, even as consumers keep their carts full.
Spotting the Real Pressure Points
You cannot look at national spending averages and assume everyone experiences the economy the same way. The aggregate data hides deep fractures.
High-income earners drive a disproportionate share of current retail momentum. They built up asset cushions, benefited from high interest rates on cash holdings, and weathered inflation easily. Meanwhile, lower-income households face severe constraints, relying heavily on credit cards to cover basic necessities.
When you read headlines about strong consumer spending, remember who buys the bulk of discretionary goods. It is a bifurcated market. One group fuels the luxury and service sectors, while another cuts back sharply on essentials.
Watch the revolving credit balances alongside retail sales reports. If spending stays high because wages grew, that is a healthy signal. If spending stays high because people rely on plastic to bridge the gap between their paycheck and their grocery bill, trouble brews underneath the surface.
What You Should Do With This Information
Stop waiting for a magical return to cheap prices. It is not happening. Instead of hoping the economy resets to past decades, focus on what you can control.
Audit your recurring subscriptions and convenience spending. Those small recurring leaks drain cash faster than a major purchase. If you have high-interest debt, prioritize paying it down aggressively while employment remains stable.
Pay attention to where your money goes each month rather than relying on broad macroeconomic headlines. Inflation might be cooling on paper, but your personal inflation rate depends entirely on your specific lifestyle choices and local market conditions. Build a financial buffer that protects you from unexpected shifts, and ignore the daily noise of financial pundits trying to predict the exact path of the next quarter.