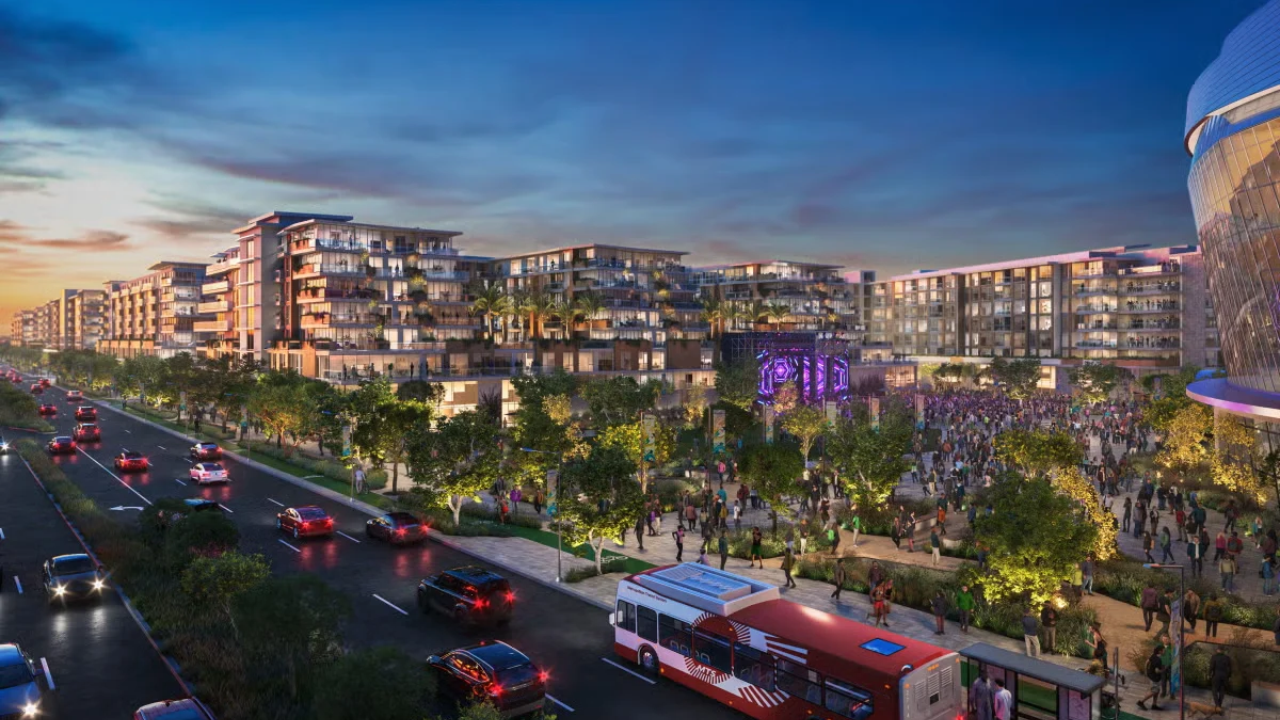
Headline figures in urban redevelopment routinely confuse gross capital expenditure with net fiscal return, and San Diego's Midway Rising proposal is a textbook example. Evaluating a $4.2 billion redevelopment across roughly 48.5 to 49.2 acres of city-owned land around the Pechanga Arena requires separating total project cost, subsidized housing commitments, ~$460 million in public and site upgrades, and ~$526.4 million in standalone arena construction from actual municipal cash flow over a 105-year horizon.
Surface-level coverage treats big headline numbers as a single balance sheet: thousands of homes, a new entertainment venue, upgraded streets and parks, and a giant check for the city. In reality, a public-private development deal on city-owned land is a multi-decade capital stack where private developers finance construction, tax-increment and public finance tools often carry infrastructure costs, affordable housing operates under strict income and subsidy rules, and ground or lease payments to the municipality depend heavily on phasing and time discounting. You might also find this similar article useful: Transboundary Haze Economics and Defensive Respiratory Demand.
Deconstructing the Competitor's Logic
Standard coverage of major civic real estate deals follows a predictable narrative arc: state the headline dollar figure, list the headline amenities, note political support or neighborhood traffic concerns, and end with a generic caution that execution matters. That structure leaves three analytical gaps. As highlighted in latest articles by Bloomberg, the effects are worth noting.
First, it treats total capital cost as if it were municipal spending or net public gain. A $4.2 billion price tag describes the estimated all-in cost of building out a multi-use district over many years. Mixing developer-financed housing, commercial space, arena construction, and public infrastructure into one number obscures who bears construction risk, who captures operating revenue, and where public subsidies enter the capital stack.
Second, it lists 4,254 homes and 2,000 affordable units as a simple count without examining the economic cross-subsidy mechanics. Market-rate multifamily units generate cash flow that can help support project economics, whereas income-restricted affordable housing relies on layered public subsidies, tax credits, or below-market financing and yields lower operating revenue per door. Treating every unit as an equal contributor to project viability misses how phasing and financing gaps shape delivery speed.
Third, it treats timeline length as background flavor rather than a financial variable. Multi-phase urban redevelopments routinely span a decade or more of construction, while ground leases or long-term agreements can stretch across 105 years. Over a century, inflation, interest rate cycles, construction cost escalation, and discounting shrink the present value of distant cash flows and widen the gap between early optimism and eventual delivery.
The Four Pillars of Project Economics
To evaluate a redevelopment of this scale rigorously, analyze it across four distinct pillars rather than a single headline number.
1. Capital Stack and Cost Allocation
Every large mixed-use development splits costs across distinct components with different funding sources and risk profiles:
- Residential and Commercial Buildout: Market-rate housing, affordable housing, and roughly 130,000 square feet of commercial or retail space carry distinct underwriting standards, construction costs, and rent trajectories.
- Entertainment Venue Economics: A modern 16,000-seat arena replacing the aging Pechanga Arena carries high upfront capital cost (estimated around $526.4 million standalone) and specialized operating risk tied to event bookings, concession margins, and ticketing agreements.
- Public and Site Infrastructure: Roughly $460 million in public upgrades and site improvements—covering roadways, bike and pedestrian paths, transit access, water, sewer, storm drainage, and roughly 14.5 acres of parks and public spaces—must be matched to dedicated funding mechanisms rather than assumed to be free.
Known fact vs. educated hypothesis: The headline figures for total project cost, housing counts, arena capacity, and infrastructure/park upgrades are part of the project's public framework. Exact final line-item costs, financing rates, and contingency draws across future phases are educated projections until final financing closes and construction contracts are executed.
2. Housing Supply and Affordability Math
Adding 4,254 homes—including up to 2,000 affordable units—on roughly 48.5 to 49.2 acres represents a major density shift from a low-intensity commercial and arena parcel to a mixed-use village. In urban economics, two mechanisms govern how that supply affects a city:
- Direct affordability impact: Deed-restricted affordable units serve qualifying lower-income households (such as households at or below 60% of Area Median Income, including dedicated permanent supportive housing), directly expanding regulated supply for cost-burdened renters.
- Citywide filtering and scarcity effects: Adding thousands of market-rate and mixed-income homes expands overall housing stock, which can temper long-run rent pressure compared to building nothing, though the effect on any single neighborhood depends on total regional demand and how quickly phases open.
A critical operational detail in municipal housing deals is ensuring affordable units are net-new on-site or clearly governed rather than merely absorbed as off-site credit transfers from elsewhere, along with enforceable timing so affordable phases do not lag behind market-rate phases.
3. Municipal Fiscal Return vs. Public Benefit
Municipalities rarely justify large land redevelopments on direct land-lease checks alone. When evaluating a 105-year agreement on public land, separate three streams:
- Direct municipal payments: Ground rent, lease revenue, or venue revenue shares paid to the city, which are sensitive to phase completion dates and independent budget estimates over time.
- Broad tax base expansion: Property tax (subject to state assessment rules), sales tax from retail and arena activity, and local economic activity generated as thousands of residents move in and commercial space operates.
- Avoided or shared public liabilities: Infrastructure upgrades and public realm improvements delivered as part of the plan, balanced against any public financing tools or municipal services required to support thousands of new residents and event visitors.
4. Phasing, Time Horizon, and Bottlenecks
A multi-phase project spanning 10 to 15+ years of buildout—and operating under a 105-year term—faces structural time risk. Early phases typically tackle initial infrastructure and foundational residential blocks, while later phases face whatever interest rates, labor costs, material prices, and consumer demand exist a decade or two later.
In practice, execution bottlenecks cluster around four operational choke points:
- Legal and environmental clearances: California Environmental Quality Act (CEQA) compliance, state statutory frameworks, and site-specific overlays (including coastal, airport proximity, and soil or environmental site conditions) can delay schedules if not tightly managed.
- Utilities and backbone infrastructure: Water, sewer, drainage, and street capacity must scale ahead of or alongside vertical construction so new housing and venue events do not overwhelm existing mains.
- Mobility and corridor congestion: Adding thousands of households plus a 16,000-seat entertainment venue near major arterials and transit corridors tests peak-hour traffic flow, parking, and pedestrian/transit connections.
- Capital market cycles: High construction costs and elevated borrowing rates can stall individual phases even after entitlements are secured.
Cause-and-Effect Chains Standard Coverage Misses
Connecting the dots reveals second-order consequences that static summaries overlook:
- Arena ticket economics vs. city cash flow: When a development partner funds or delivers a new arena and retains ticket or venue revenue to recoup arena costs after completion (after paying a share during the legacy venue period), near-term event cash flow goes toward venue cost recovery rather than acting as an immediate windfall for the city's general fund.
- Construction disruption before housing relief: Traffic and circulation impacts along surrounding corridors begin during site work and early construction phases, while new housing units arrive incrementally over years—creating a period where residents experience construction friction before full housing supply and park amenities mature.
- Phasing risk on long-term revenue models: Because lease or development payments tied to future phases depend on when each phase finishes, any multi-year delay in later phases pushes projected payments further into the future and reduces their inflation-adjusted value.
- Density plus open space trade-offs: Packing 4,254 homes, commercial space, an arena, and ~14.5 acres of parks and public space onto roughly 49 acres creates tight spatial competition on-site, making park design quality, active recreation space, and airport/site constraints decisive for livability.
Step-by-Step Due Diligence Framework
Anyone evaluating a mega-project deal—whether an analyst, policymaker, investor, or resident—can audit the numbers using a repeatable five-step sequence:
- Unbundle the headline dollar figure. Separate total development cost ($4.2B) from public/site upgrades (~$460M), standalone venue cost (~$526.4M), and vertical residential/commercial costs. Never treat total project cost as public money spent or public money earned.
- Audit the affordable housing mechanics. Verify the exact unit count (2,000 affordable out of 4,254 total), target income tiers, permanence duration, net-new status versus off-site transfers, and phasing milestones.
- Map infrastructure funding sources. Identify which upgrades are funded by developer equity, public financing districts, grants, or city budgets, and check whether backbone utility and street work precedes occupancy.
- Stress-test the multi-phase timeline. Model what happens to project feasibility and city revenue if Phase 2 or Phase 3 slips by three to seven years due to financing or construction costs.
- Separate direct cash flow from spillover value. Compare projected direct municipal cash inflows over the agreement term against broader economic activity, tax generation, and neighborhood externalities like traffic and transit access.
Limitations and Analytical Blind Spots
No single framework captures every variable in a multi-decade urban redevelopment. Long-range financial models rely on assumptions about construction inflation, operating expenses, interest rates, and lease performance that become less precise the further out the horizon extends—especially across a 105-year window. Public budget analyses often report nominal or present-value estimates without showing every sensitivity case, and project scope details can evolve during final design, permitting, and phase financing. Treating any single projection as certainty is an analytical error; treating it as a bounded scenario range is disciplined practice.
Strategic Play for Stakeholders
City leaders and oversight bodies should tie phase-by-phase entitlements and public financing draws to hard delivery milestones—specifically verified net-new affordable housing commitments, completed backbone infrastructure, and usable public open space—while publishing transparent annual phase-tracking reports that compare actual delivery and net municipal cash flow against baseline projections.